2026 Federal Tax Brackets Explained
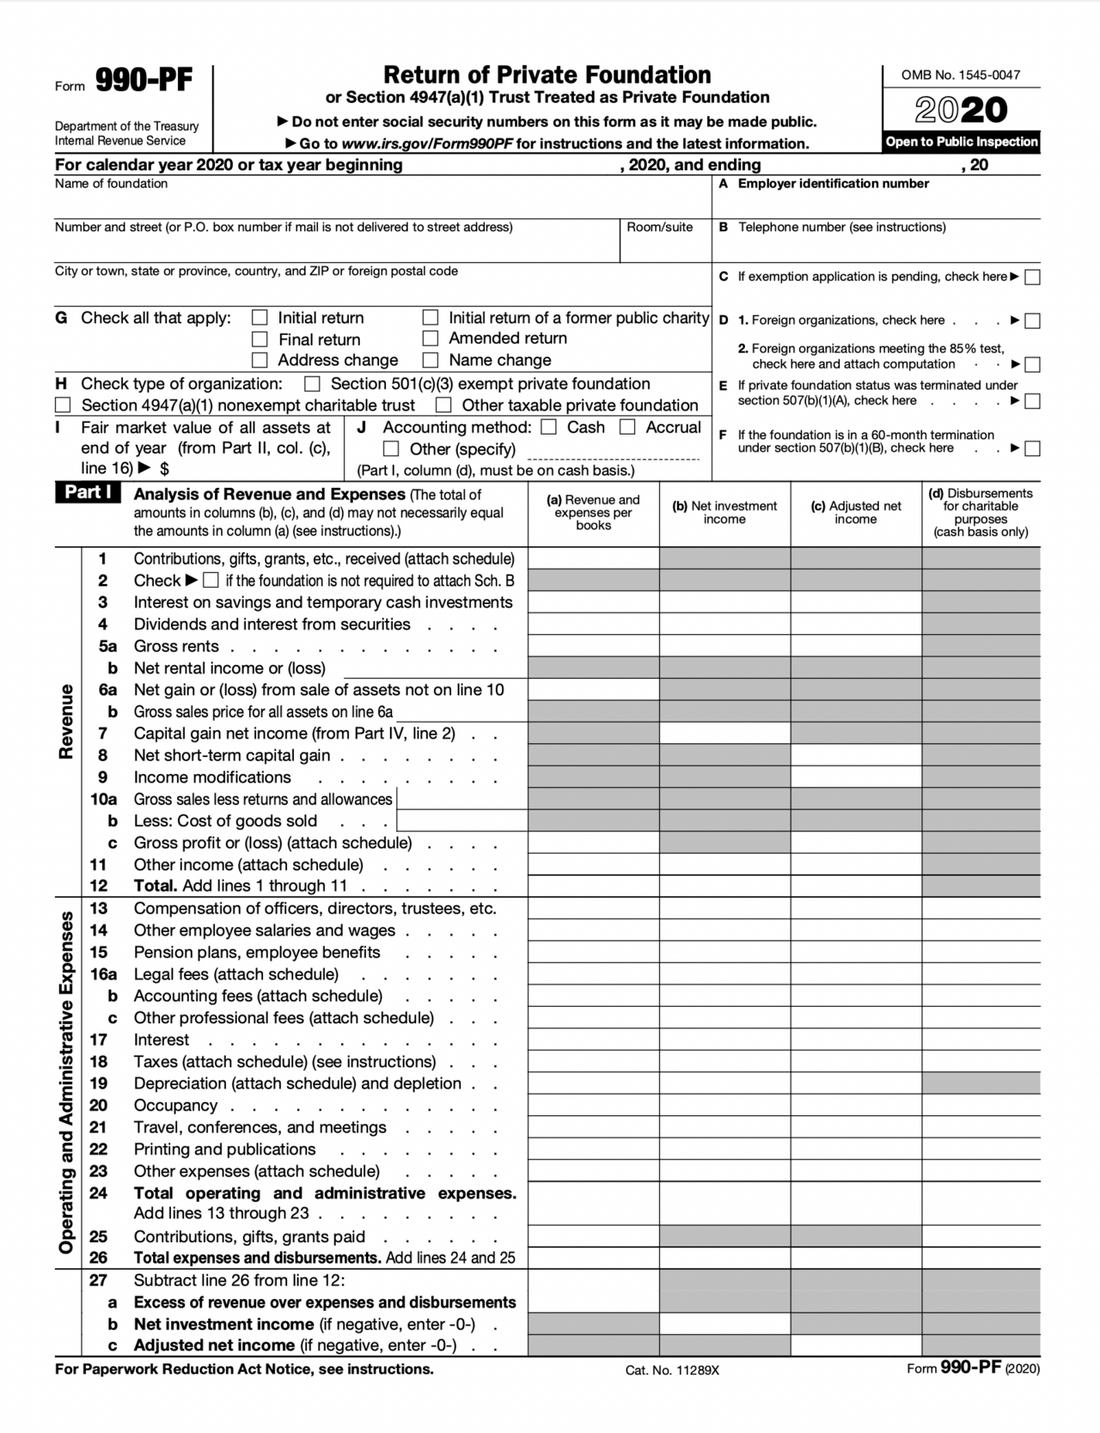
For tax year 2026 there are seven federal income tax rates: 10%, 12%, 22%, 24%, 32%, 35%, and 37%. The thresholds come from IRS Revenue Procedure 2025-32, announced in IRS news release IR-2025-103 on 9 October 2025. The adjustments cover more than 60 tax provisions and generally apply to tax returns filed in 2027, which are the returns for tax year 2026. The seven rates are now permanent under the One Big Beautiful Bill Act (Public Law 119-21, signed 4 July 2025).
The one idea that matters
Tax brackets are marginal. Each rate applies only to the income inside that band, so your top (marginal) rate is never the rate you pay on all your income. If you are a single filer, the 22% rate applies only to the part of your taxable income above $50,400, not to the first $50,400. That first part is taxed at 10% and 12%.
The seven rates
The 2026 rates are 10%, 12%, 22%, 24%, 32%, 35%, and 37%. Notice the jump from 12% to 22%: there is no 15% or 20% bracket in the current schedule. The top rate of 37% applies only to taxable income above the highest threshold for your filing status. Because the brackets are marginal, two people with the same total income can owe different amounts if their filing status or deductions differ.
The brackets apply to taxable income, which is income after the standard or itemized deduction, not to gross pay. For 2026 the standard deduction is $16,100 single, $32,200 married filing jointly, and $24,150 head of household, so a single filer with $66,100 of gross income and no other adjustments or deductions has $50,000 of taxable income.
Single filers
For single filers in 2026, the 10% rate applies to taxable income up to $12,400. The 12% rate applies to income over $12,400. The 22% rate starts over $50,400, the 24% rate over $105,700, the 32% rate over $201,775, the 35% rate over $256,225, and the 37% rate over $640,600.
A single filer with $60,000 of taxable income is therefore taxed at 10% on the first $12,400, 12% on the part from $12,400 to $50,400, and 22% only on the last $9,600. The tax is $1,240 plus $4,560 plus $2,112, a total of $7,912. The effective rate is about 13.2%, even though the marginal rate is 22%.
Married filing jointly
For married couples filing jointly in 2026, the 10% rate applies to taxable income up to $24,800, the 12% rate to income over $24,800, the 22% rate over $100,800, the 24% rate over $211,400, the 32% rate over $403,550, the 35% rate over $512,450, and the 37% rate over $768,700.
Joint thresholds are roughly double the single thresholds for the lower brackets, which is why a married couple with the same combined income as a single filer usually owes less tax. A couple with $100,000 of taxable income pays 10% on the first $24,800 and 12% on the rest, a total of $11,504, an effective rate of about 11.5%.
Head of household and married filing separately
For heads of household in 2026, the 10% rate applies up to $17,700, the 12% rate to income over $17,700, and the 22% rate over $67,450. The 24% rate starts over $105,700, the 35% rate over $256,200, and the 37% rate over $640,600. The exact point where the 24% band ends for heads of household is not stated here, because the sources consulted for this site disagreed on that one figure and it could not be confirmed from the IRS summary; readers should check the tables in Revenue Procedure 2025-32 on irs.gov.
For married couples filing separately, the 37% rate starts over $384,350, and the other thresholds are half the joint thresholds. Filing separately is usually more expensive than filing jointly, and it also blocks some credits and deductions, so it is worth comparing both ways before choosing, as the filing statuses guide explains.
A worked example
Take a single filer with $80,000 of taxable income in 2026. The first $12,400 is taxed at 10% ($1,240). The next $38,000, from $12,400 to $50,400, is taxed at 12% ($4,560). The next $29,600, from $50,400 to $80,000, is taxed at 22% ($6,512). The total is $12,312, an effective rate of about 15.4%. The filer is in the 22% bracket, but only about a third of the income is actually taxed at 22%.
That is why a pay rise that pushes you into a higher bracket never makes you poorer. Only the income above the threshold is taxed at the higher rate, so your take-home pay still rises. The bracket your top dollar falls in is your marginal rate, and it is the rate that matters when you are deciding whether extra income, or an extra deduction, is worth having.
Sources: Internal Revenue Service, IR-2025-103, 9 October 2025, and Revenue Procedure 2025-32, https://www.irs.gov/newsroom/irs-releases-tax-inflation-adjustments-for-tax-year-2026-including-amendments-from-the-one-big-beautiful-bill.